By Autumn Demberger, AgInvesting Media
The bags are packed, the sessions picked. Global AgInvesting Europe commences this Oct. 12-13 at the Rosewood Hotel in London.
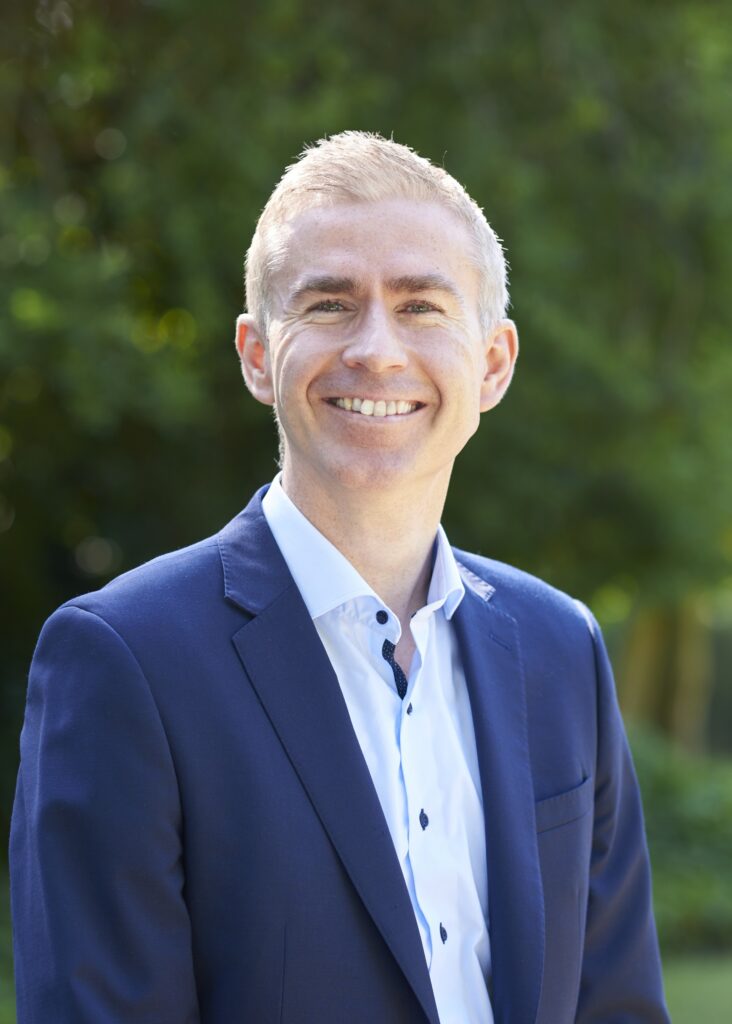
Events kick off on Monday with keynote speaker Michael Haverty, partner and senior research consultant for The Andersons Centre, as he aims to outline a global overview of the agriculture industry from a European perspective.
“In many ways, agriculture is now experiencing a “perfect storm” in that geopolitics, climate change and a range of other issues … are having major impacts on how the sector is performing and is likely to perform in the future,” Haverty said. “Europe feels this more than most because it imports much of its energy, fertiliser and protein feed, so every external shock arrives through input prices. That is why I framed the talk around one question: is resilient the new efficient?”
Below, Haverty provides additional insight and what GAI Europe attendees can expect at this year’s event.
Global AgInvesting: As the opening keynote for GAI Europe, what initially drew you to selecting your topic? What makes this something that those in the industry should want to hear about right now?
Michael Haverty: At The Andersons Centre, our Business Research team has a core focus on examining the macroeconomic and policy issues shaping UK and European agriculture. This, combined with our farm-level perspectives from our farm consultancy colleagues who advise a wide variety of farmers on a daily basis, means that we are ideally positioned to offer an informed perspective on how the key macro issues shaping agriculture globally impact at the farm level. This is especially pertinent given that the 2020s have turned out to be the “decade of disruption” across so many areas.
In many ways, agriculture is now experiencing a “perfect storm” in that geopolitics, climate change and a range of other issues (e.g. disease, consumer demand, support reform etc.) are having major impacts on how the sector is performing and is likely to perform in the future. Europe feels this more than most because it imports much of its energy, fertiliser and protein feed, so every external shock arrives through input prices. That is why I framed the talk around one question: is resilient the new efficient? It matters now because the rate-cutting cycle has stalled, oil is around 40% above its pre-war level, with diesel even higher. For anyone considering investing in the sector, having a “finger-on-the-pulse” assessment is crucial.
GAI:Specifically thinking about a European audience, how would you describe the current health of the global economy, and what are the biggest economic headwinds facing agriculture today?
MH: Despite all the challenges, it could be argued that the global economy remains fairly resilient with IMF forecasting global growth at 3% for 2026. However, much of this is driven by growth outside of Europe and in high-growth regions such as Asia-Pacific. For Europe, the inflationary challenge looms large as a key headwind particularly given its reliance on imported inputs. In a UK context, our Agflation estimates indicate that input costs now are some 33% higher now than the start of 2021, and are rising again. This exerts significant profitability pressure at a farm-level and coming at a time when the prices of several agricultural outputs (e.g. milk and cereals) are lower than they were a few years’ back.
Linked with heightened inflation, interest rates have also risen in recent years and this is affecting farmers’ willingness to invest. Furthermore, support payments to farmers, which are crucial in some sectors are also coming under pressure, particularly as debt-to-GDP ratios have increased in the past decade and support budgets face competition from several other areas. This has been especially prevalent in the UK which has had to deal with the fall-out from Brexit and new trade deals with the likes of Australia and New Zealand which are exerting pressure in some areas.
GAI: From your perspective, where are investors and financial institutions currently “placing their bets” when it comes to the future of agriculture?
MH: As a firm, we do not advise on where capital is allocated, so I will leave that to others at the conference. What we do see, through working with farm businesses every day, is where investment is needed and where it is paying off. Three areas stand out: reducing reliance on bought-in inputs through precision fertiliser, and on-farm energy; storage and water management. These help a business ride out supply and weather shocks and address animal health issues. We are also seeing restructuring quietly accelerate as support tightens, with land and businesses moving to the best operators.
GAI: If you could choose one thing that attendees, and online readers, take away from your discussion, what would it be and why?
MH: Investors and attendees need to actively consider the resilience of the businesses that they invest in. There needs to be a balance between being resilient and being efficient – both are important and resilience can be thought of as efficiency measured over a multi-year cycle and not a single year. The businesses that look best in a good year, with minimal inventory, maximum leverage and one big customer, are often the most fragile when conditions turn, or if one key area of their operation experiences a major outage or failure.
For anyone allocating capital, that means three things: value on mid-cycle returns, or averages over a multi-year period and not peak earnings; stress-test leverage at varying interest rates, and test currency exposure and exchange rate swings also.
Where possible, give credit in valuations for initiatives/activities that provide resilience, such as adequate working capital, storage, secure inputs and good disease status. Of course there is a balance to be struck, but strategic buffers/contingency stocks are not waste, they are what could sustain a business through the next shock.
GAI: What’s one question you hope your audience asks you after your discussion? Or, in other words, what should they continue to be thinking about long after the close of the conference?
MH: How can one measure resilience when considering agricultural investments? A key aspect to this is determining whether the business is being efficient in the short-term but is exposed to shocks over the longer term. For instance, in a good year, an efficient business might appear if it is out-performing based on the accounts. But this can hide future challenges. One needs to examine how long could the business keep going on its own feed, input stocks (e.g. fertiliser, water) and storage if supply were disrupted? Could it service its debt at interest rates that were 1-2 percentage points higher? How much of its cost base depends on imported energy, fertiliser and feed? How reliant is it on one customer or one export market? And how good are its disease status and biosecurity? None of these are necessarily complex questions to answer but you need to probe these issues before investing.
The content put forth by Global AgInvesting News and its parent company Arc Network LLC is intended to be used and must be used for informational purposes only. All information or other material herein is not to be construed as legal, tax, investment, financial, or other advice. Global AgInvesting and Arc Network LLC are not a fiduciary in any manner, and the reader assumes the sole responsibility of evaluating the merits and risks associated with the use of any information or other content on this site.